What is Form 2086 and when does CoinTracking generate it?
Form 2086 is the French annex on which private individuals declare their gains and losses from disposals of digital assets under Article 150 VH bis CGI. CoinTracking fills it in automatically from the France tax report and attaches it after the transaction sections.
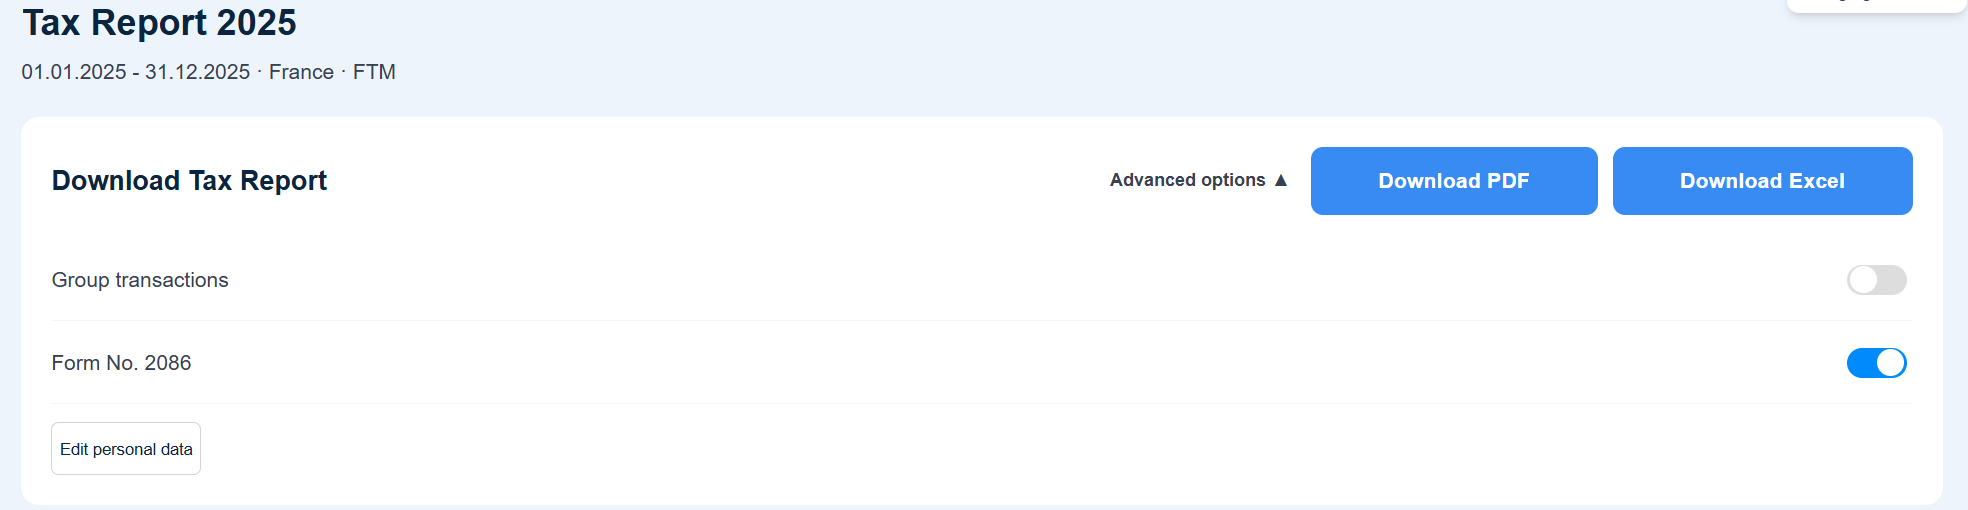
How to get it: create the France tax report and enable the Form No. 2086 toggle under Advanced options. The form is then part of the PDF export.
What goes into it: only taxable disposals against fiat currency. Each taxable disposal becomes one Cession column. The following are not reported on the form:
- Crypto-to-crypto exchanges without a cash adjustment (tax-deferred in France)
- Margin, derivative and futures transactions
- Settlement fees, borrowing fees and other fees
- Provide liquidity and Return LP token
For the tax rules behind the report, see Guide to Navigating and Understanding Your Tax Report (France).
Lines 211-218: the disposal (one column per cession)
| Line | Form label | Meaning | Where CoinTracking takes it from |
|---|---|---|---|
| 211 | Date de la cession | Date of the sale | Date sold of the taxable transaction |
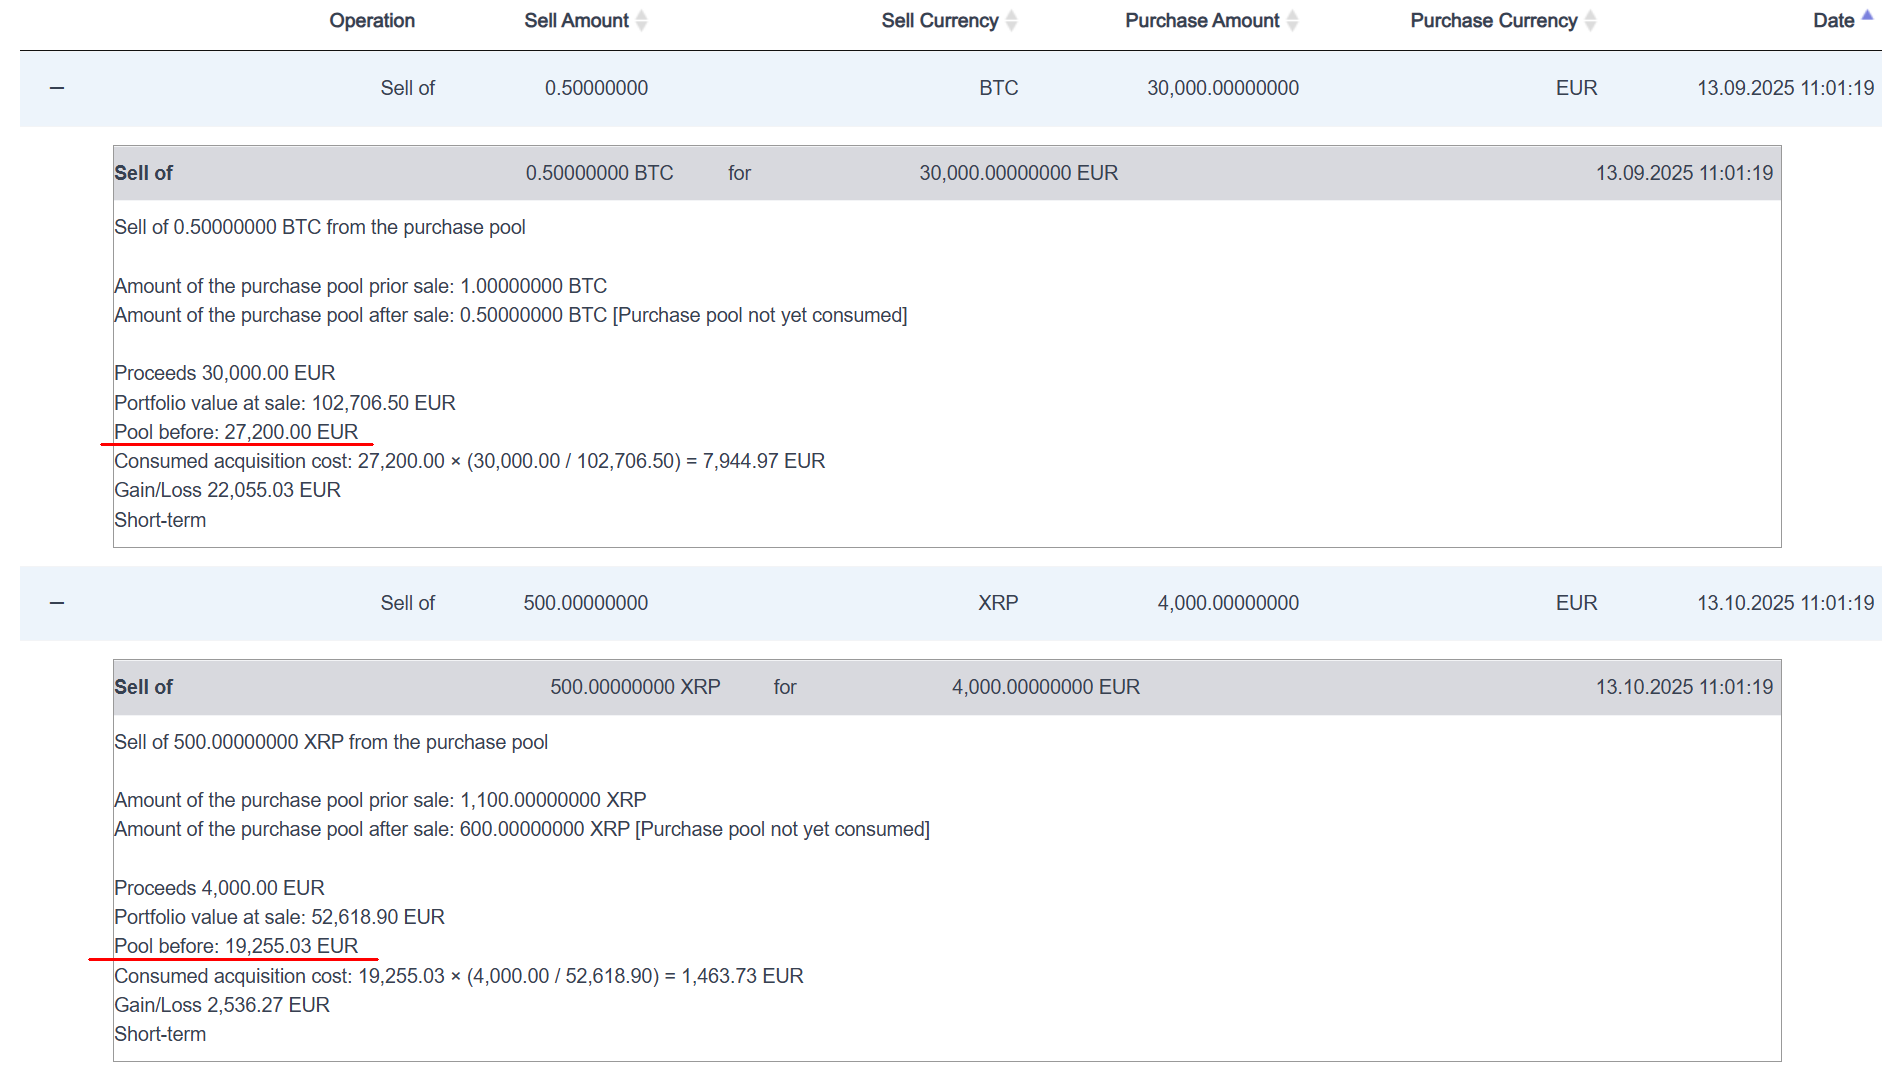
| 212 | Valeur globale du portefeuille au moment de la cession | Market value in EUR of all crypto-assets held, immediately before the disposal (the coins being sold are still included) | "Portfolio value at sale" shown in the detailed calculation of the sale |
| 213 | Prix de cession | Sale price | Proceeds in EUR of the taxable transaction |
| 214 | Frais de cession | Disposal fees | Fee value of the disposal from the detailed fee report |
| 215 | Prix de cession net des frais | Sale price net of fees | 213 - 214 |
| 218 | Prix de cession net des frais et soultes | Sale price net of fees and cash adjustments | 213 - 214 - 216 (or 213 - 214 + 216) |
Why line 212 is not the sale price × holdings. The French formula allocates a share of the acquisition cost to each disposal in proportion to how much of the portfolio is sold. The denominator is the market value of the whole portfolio at that moment, so CoinTracking values every coin held with its historical price, not with the price actually obtained in the trade.
Lines 220-224: the acquisition cost and the gain
France does not match a sale to a specific purchase lot. Every taxable disposal consumes a fraction of the acquisition cost of the whole portfolio, and that fraction is removed from the pool for the next disposal. Lines 220-223 track this pool.
| Line | Form label | Meaning | Where CoinTracking takes it from |
|---|---|---|---|
| 220 | Prix total d'acquisition | The total acquisition price of the entire portfolio of digital assets (under Art. 150 VH bis CGI), as of immediately before the relevant disposal. It covers all acquisitions since the beginning, not just those of the asset being sold. | Sum of the cost basis of all acquisitions up to the disposal |
| 221 | Fractions de capital initial contenues dans le prix total d'acquisition | The portion of that total acquisition price that has already been "used up" by earlier disposals. With each taxable disposal, part of the acquisition cost (the capital fraction) is attributed to the sale price. Those fractions are deducted again for later disposals, so the same acquisition cost is not counted twice. | Can be determined in the detailed calculation under consumed acquisition cost |
| 223 | Prix total d'acquisition net | Total net acquisition cost | 220 - 221 - 222 |
| - | Plus-values et moins-values | Gain or loss of this cession, with sign | 218 - [223 × (217 ÷ 212)]; equals Gain/Loss in EUR in the tax report |
| 224 | Plus-value ou moins-value globale du déclarant 1 | Total gain or loss of all cessions of Déclarant 1 | Sum of the gain/loss lines, equals the total in the tax report |
Line 220 shows the total acquisition price of the portfolio. Line 221 deducts the fractions of initial capital already used in previous disposals.
Example
Transactions for the example:
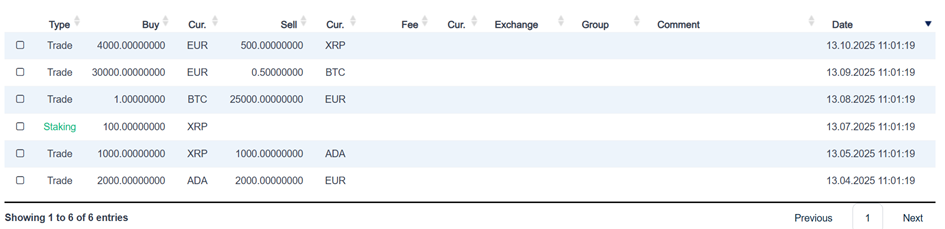
| Date | Transaction | Effect on Form 2086 |
|---|---|---|
| 13.04.2025 | Buy 2,000 ADA for 2,000.00 EUR | +2,000.00 EUR acquisition cost (line 220) |
| 13.05.2025 | Exchange 1,000 ADA → 1,000 XRP | Crypto-to-crypto: not on the form, line 220 unchanged |
| 13.07.2025 | Staking reward 100 XRP, value 200.00 EUR | +200.00 EUR acquisition cost (line 220), listed in section 2 of the report |
| 13.08.2025 | Buy 1 BTC for 25,000.00 EUR | +25,000.00 EUR acquisition cost (line 220) |
| 13.09.2025 | Sell 0.5 BTC for 30,000.00 EUR | Cession 1 |
| 13.10.2025 | Sell 500 XRP for 4,000.00 EUR | Cession 2 |
Line 220: 2,000.00 + 200.00 + 25,000.00 = 27,200.00 EUR.
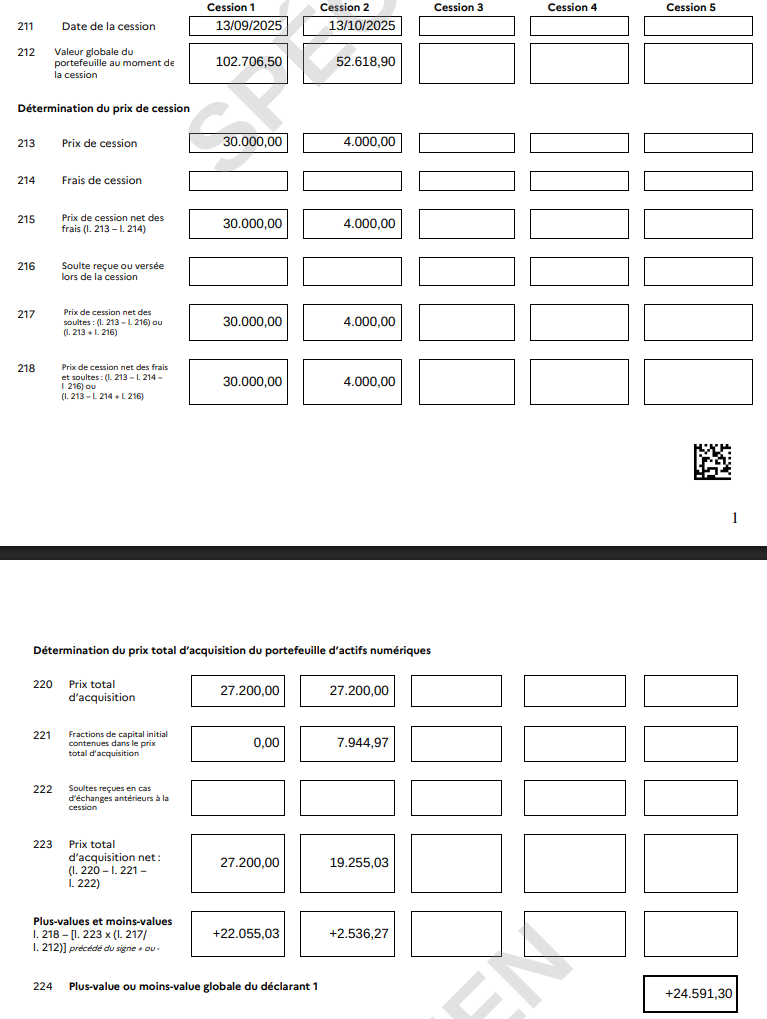
| Line | Cession 1 (13.09.2025) | Cession 2 (13.10.2025) | How it is calculated |
|---|---|---|---|
| 212 | 102,706.50 | 52,618.90 | Portfolio value at sale (detailed calculation) |
| 213 | 30,000.00 | 4,000.00 | Proceeds |
| 214 | | | No fees on either trade |
| 215 / 217 / 218 | 30,000.00 | 4,000.00 | 213 - 214 - 216 |
| 220 | 27,200.00 | 27,200.00 | Total acquisition cost, unchanged |
| 221 | 0.00 | 7,944.97 | Cost consumed by Cession 1 |
| 223 | 27,200.00 | 19,255.03 | 220 - 221 (= Pool before) |
| Cost consumed | 7,944.97 | 1,463.73 | 223 × 217 ÷ 212 |
| Gain/loss | +22,055.03 | +2,536.27 | 218 - cost consumed |
Cession 1: 30,000.00 - 27,200.00 × (30,000.00 ÷ 102,706.50) = 30,000.00 - 7,944.97 = +22,055.03 EUR
Cession 2: 4,000.00 - 19,255.03 × (4,000.00 ÷ 52,618.90) = 4,000.00 - 1,463.73 = +2,536.27 EUR
The resulting Form 2086 and the detailed calculation of each sale in the tax report: